You tell yourself you’ll save whatever is left at the end of the week. Then the week ends, an ordinary expense pops up, and there’s nothing left to move. If that sounds familiar, you don’t need a bigger promise to yourself. You may need a smaller, easier action that happens before the week gets away from you.
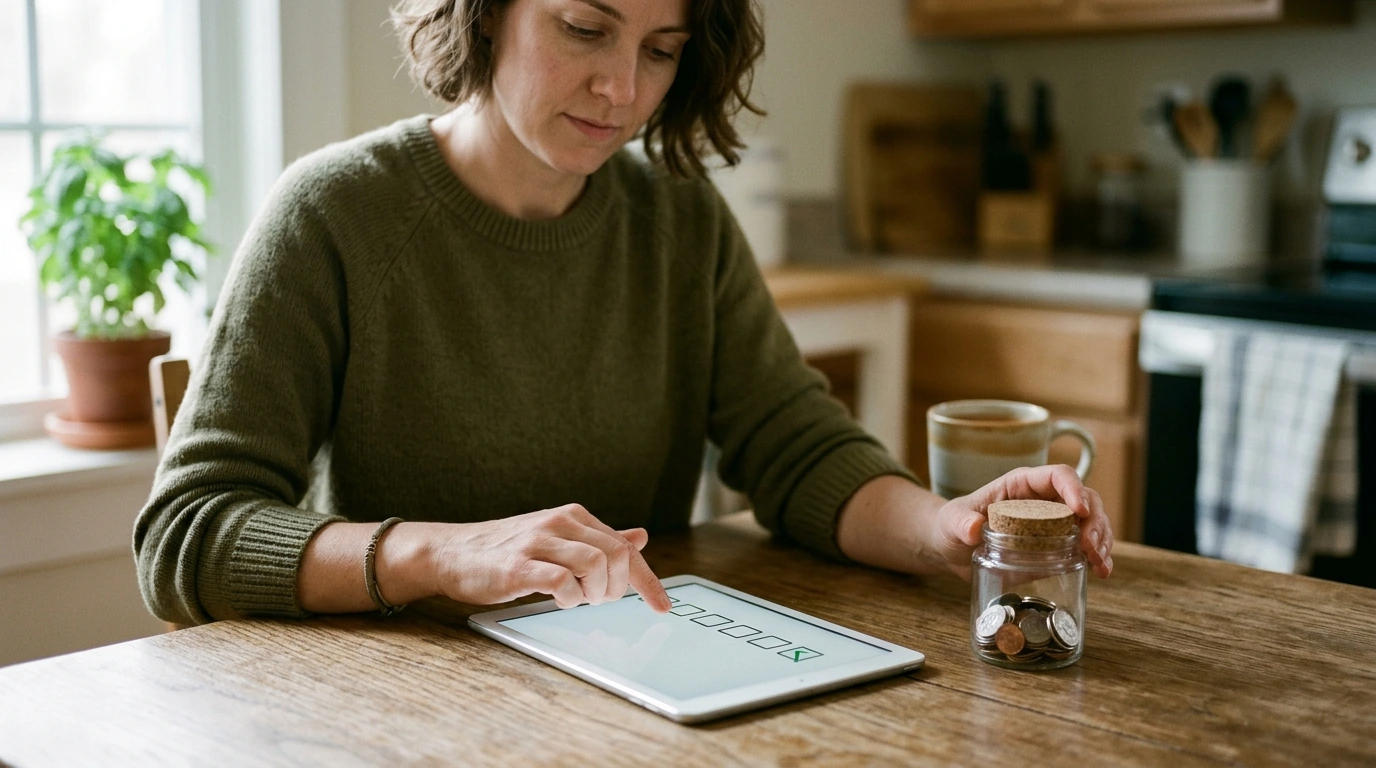
Saving can begin with a repeatable amount, a reliable cue, and a way to notice that you followed through. Keep this simple checklist in mind: choose an amount, choose a day, make the move, and mark it done.
Pick an amount that fits an ordinary week after essential expenses—even if that amount is one dollar. Your first goal isn’t an impressive balance. It’s practicing a saving action you can repeat without making the rest of your week harder.
Choose one day each week and move that amount to your savings on that day. If you get paid every other week, an every-other-week move may fit better. The point is to make the decision once rather than renegotiate it every time you remember to save.
It’s fine to start below the amount you eventually hope to save. Once the action feels manageable and you know what your expenses allow, you can decide whether to increase it. For now, a completed small deposit counts.
“Save sometime this week” asks you to remember at a random moment. A cue gives the action a place in your routine. You might move money on payday, right after a weekly account check, or on the same day you review upcoming bills.
A phone reminder can be enough. If your income and bills are predictable, a scheduled transfer may suit you; if they vary, a reminder to decide how much you can move may be more useful. Either way, leave room to cover essentials first.
For a broader look at everyday money decisions, the Consumer Financial Protection Bureau’s Money as You Grow resources offer activities and conversation starters. Our approach here is deliberately small: give your next saving action a time and make it easy to recognize.
Different obstacles call for different moves. You don’t need to use every trick below, and none is a rule you must follow. Pick the one that addresses what usually happens when you intend to save but don’t.
| When this happens | Try this mind hack | Easy next step |
|---|---|---|
| Saving feels too big | Shrink the starting line | Choose an amount you can comfortably repeat. |
| You forget to save | Attach it to a cue | Set a reminder for payday or another regular day. |
| An impulse purchase is tempting | Add a pause | Wait a day, then decide whether you still want it. |
| Progress feels invisible | Make the action visible | Check off each deposit, however small. |
The one-day pause is a choice, not a ban on spending. You can still buy something you value after thinking it over. If you decide against it and the money is available, you could move a portion to savings—but you don’t have to turn every purchase decision into a deposit.
A savings balance matters, but it doesn’t tell the whole story. Balances can grow slowly, especially when you’re starting small or need to use savings for a real expense. Track completed actions too: each time you make your planned deposit, put a check on a calendar or add a note on your phone. That record shows you’re building a routine even when the dollar amount is modest.
Giving the money a specific name can make the action feel less abstract. “Car repair cushion,” “holiday travel,” or “a little breathing room” may mean more to you than a general label like “savings.” Choose a name that reflects your priorities; it doesn’t need to sound ambitious to anyone else.
If you’d rather keep your small actions in one place, our Fun Mind Hacks to Build a Saving Habit That Sticks digital checklist is an optional tool. You can also use a calendar, notebook, or free note on your phone. What matters is choosing a method you’ll actually return to.
Some people like applying the same check-it-off approach to other goals. If that sounds useful beyond saving, our Fuel Up & Fire Ahead entrepreneur action checklist is another optional digital checklist, aimed at entrepreneurial action rather than money management. There’s no need to add another tool if one simple savings tracker is enough.
Expenses change. A tight week may call for a smaller deposit or no deposit at all. That’s a financial decision, not a failure of character. Avoid putting money aside if doing so would leave you short on essentials or push you toward debt for routine costs.
Once a month, take a few minutes to review what worked. Was your chosen amount comfortable? Did your cue arrive at a useful time? Would a different day make the action easier? The FDIC’s Money Smart resources can help you explore budgeting and saving more broadly when you want to go further.
Start with an amount that fits comfortably after essential expenses, even if it is only a dollar. Repeating a small deposit matters more than choosing an ambitious one.
Resume when you can without trying to make up the missed deposit. If it keeps happening, consider a smaller amount or a more reliable cue.
A checklist can make your next action clear and give you a visible record of follow-through. It is most useful when the steps fit your finances and routine.


Leave a comment